Company News, Deals

On 31 October 2025, the Department for Culture, Media and Sport (DCMS) announced that audit and independent examination thresholds will increase. Shortly after, on 10 November 2025, the Scottish Government introduced similar reforms through the Charities Accounts (Scotland) Amendment Regulations 2025.
These adjustments aim to ease the regulatory burden on smaller charities and reflect the evolving financial landscape.
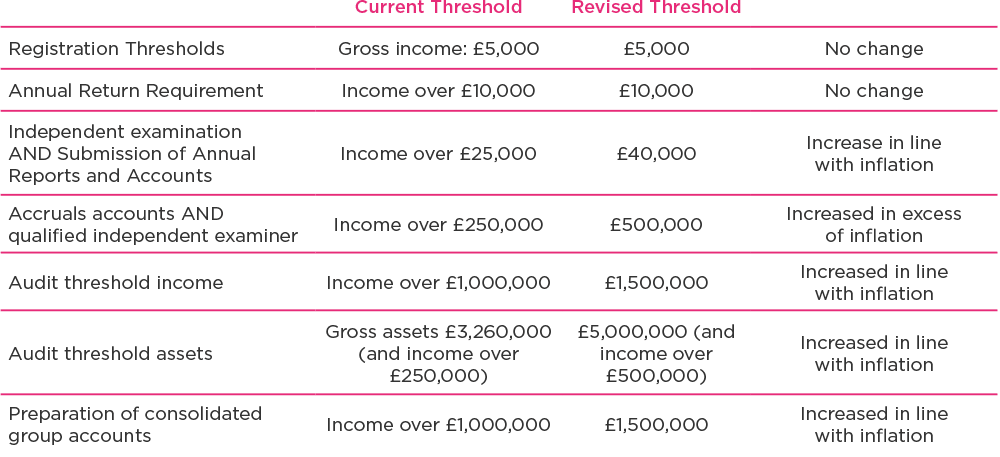
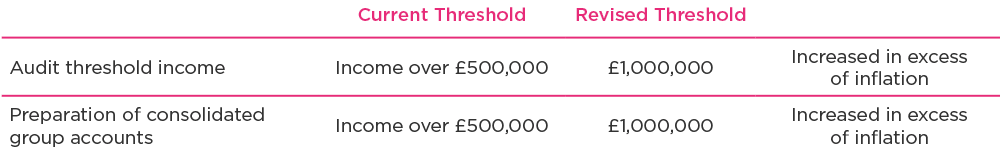
We have included in the tables below, a comparison of the current thresholds and the revised thresholds.
Whilst registration and annual return thresholds have not been changed the independent examination and audit thresholds have been raised.
The threshold for accruals accounts and the requirement for a qualified independent examiner has risen above inflation and aligns with the SORP lowest tier.
The Scottish reforms double the thresholds for audits and consolidated accounts.
These changes are not expected to come into effect until at least 1 October 2026 as a statutory instrument will be required to implement the changes. Charity Commission guidance to accompany these will be updated in due course.
These changes are effective for accounting periods beginning on or after 1 January 2026. The SORP acknowledges the diversity of thresholds that charities will have the consider annually to ensure that they are complying with SORP and legal requirements.
Please get in contact with us if you’d like to know how these changes might impact your charity.
Please note that this content is not intended to give specific technical advice. It is designed to highlight some of the key changes rather than provide an exhaustive explanation of the topics. Professional advice should always be sought before action is either taken or refrained from as a result of information contained herein.
Michael joined PEM as an ACA trainee in August 2008 after gaining a First Class degree in Mathematics and MSc from the University of Exeter. Having qualified as a Chartered Accountant in 2011, he now manages a large portfolio of audit and accounts clients. Michael has been a Responsible Individual (RI) since 2020 and was appointed Partner in October 2022.